

Simple Checkbook Ledger analysis by Appwee
I have always liked the idea of a digital checkbook because it solves a very ordinary problem: remembering where money went without turning a simple spending habit into a full budgeting project. Simple Checkbook Ledger, a finance app from Teelu Apps, takes that focused approach. Its store summary is “Manage your accounts with ease,” while the short description calls it “Simple Checkbook,” and that combination gives a fair impression of its purpose. This is meant for recording and following account activity, not for replacing a complete banking service.
After spending time with it, my impression is that its appeal comes from restraint. The app is aimed at people who want a personal ledger they can consult regularly, especially when they prefer to see transactions in a checkbook-style format rather than inside a busy financial dashboard. The main question is not whether it can do everything, but whether a straightforward ledger is enough for the way you handle money.
How Simple Checkbook Ledger fits into everyday money tracking
Simple Checkbook Ledger belongs in the finance category, but I would place it at the practical, hands-on end of that category. It is closer to a digital register than to an investment platform, bill-negotiation service, or automatically connected banking hub. That distinction matters because the best experience depends on your willingness to keep your records current.
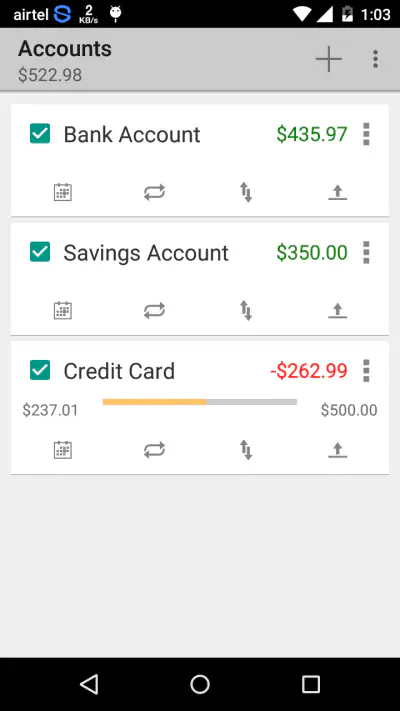
I found the checkbook idea useful for situations where the balance shown by a bank account is not the same as the amount I can safely spend. Pending purchases, checks, cash withdrawals, and small transactions can easily create a gap between what has cleared and what I have already committed. A ledger gives those entries a place before the bank statement catches up.
A realistic example is a household account used for groceries and recurring expenses. I might enter a supermarket purchase immediately, record a check that has not cleared, and then compare the running balance with the bank later. That extra step can prevent the familiar mistake of treating the displayed bank balance as available money. The app is most useful when it becomes part of that routine rather than something opened only after a problem appears.
The developer is Teelu Apps, and the application has been available since August 3, 2016. Its current version is 3.5, and it requires at least iOS 11. That makes compatibility worth checking before installation, particularly if the device is older or has not been updated in a long time. The age rating is Everyone, which fits the app’s personal finance purpose.
What the free price really means
Simple Checkbook Ledger is free to download, so trying its basic approach does not require an upfront payment. That is important for this type of utility: a person can decide whether manual ledger keeping suits them before committing money. The app also lists in-app purchases at $1.99 per item, so free access and paid value should be considered separately.
I would not treat the free price as proof that every useful capability is included. The sensible way to approach it is to install the app, test the workflow with a small set of accounts or transactions, and only then decide whether an optional purchase improves the experience enough to justify it. Because each item has its own price, the value depends on what you personally need rather than on assuming that a paid tier is automatically necessary.
This is also where the app differs from many finance products that push users toward subscriptions or broader financial services. Here, the initial barrier is low. On the other hand, someone looking for a fully automatic system may find that free access does not change the central responsibility: accurate records still depend on the user.
What value comes from a ledger instead of automation
The strongest value is visibility. A manually entered register encourages me to think about each transaction rather than allowing spending to disappear into a synchronized feed. That can be especially helpful for cash, checks, shared household purchases, or payments made from an account that is not connected to a financial service.
There is also a useful separation between recording an event and waiting for it to appear in a bank account. If I write a check today, the ledger can reflect that commitment immediately. If I later see the transaction clear, I can reconcile the two moments. That habit gives the running balance more meaning than a bank balance viewed in isolation.
Another non-obvious benefit is that manual entry can expose recurring mistakes in my own behavior. If I repeatedly forget small purchases, enter transactions late, or use the wrong account, the ledger makes the pattern visible through the act of maintaining it. An automated app may be more convenient, but convenience can hide the reason a balance keeps surprising me.
For a person managing one or several personal accounts, the app can therefore act as a lightweight control panel. It does not need to become a complete financial archive. A short daily check, followed by a more careful comparison with statements, may be enough to make spending decisions less reactive.
A practical workflow that gets more from the app
I would begin by deciding what the ledger is responsible for. If I want it to track every account, I need a consistent rule: enter transactions when they happen, not when I remember them. If I only need it for checks and cash spending, I would keep the scope narrow. Mixing a carefully maintained account with an incomplete one can make the overall picture misleading.
My preferred routine would be to record the payee or purpose in plain language, enter the amount immediately, and review the running balance before making a larger purchase. At the end of a week, I would compare the entries with the bank activity and mark any difference for follow-up. This is a more reliable workflow than trying to reconstruct a month of spending from memory.
A second useful technique is to treat uncleared items as commitments rather than ordinary historical entries. A check or scheduled payment may not have left the account yet, but it still affects what I can safely spend. Keeping that distinction in mind is one of the main reasons to use a checkbook-style app instead of relying only on a statement.
I would also avoid using the app as the sole record for important financial obligations until I had established a backup habit. A ledger is only helpful when entries are correct and available when needed. Comparing it with official account statements remains essential, especially before paying bills or moving a large amount of money.
Where the experience can feel limited
The same manual focus that makes the app clear can also become its biggest weakness. If I make many card purchases every day, entering each one may feel like work. A bank-connected finance app may be a better choice for someone who wants transactions imported automatically, categorized with minimal effort, and viewed across several institutions.
There is also a difference between tracking account movement and understanding a complete financial picture. A checkbook ledger can help me know what is available in a particular account, but it is not automatically the same as a spending plan, debt strategy, investment overview, or household budget. People who need those broader tools should compare this app with a dedicated budgeting service rather than expecting the ledger to grow into one.
Accuracy is another trade-off. With a manual register, a missed entry, duplicated transaction, or mistyped amount can affect every later balance. I consider that manageable when the number of transactions is modest, but it becomes more demanding as activity increases. The app can support discipline; it cannot provide that discipline for me.
The public average rating is 3.4 from around 2.5 thousand ratings, with about 1.2 thousand written reviews. I read that as a reason to keep expectations measured. The app has a substantial history and more than 100 thousand installs, but its audience is likely to be divided between people who appreciate a focused checkbook and people who expect modern automation from a finance app. Those are very different expectations, so the rating alone does not tell me whether it will suit a particular user.
Who is most likely to get real value
I would recommend trying Simple Checkbook Ledger if you manage a small number of accounts and want direct control over the record. It is a good fit for someone who still uses checks, handles cash, shares expenses within a household, or wants to track an account that does not fit neatly into an automated banking setup.
It may also suit people who find larger budgeting apps distracting. Some financial tools present charts, categories, goals, alerts, and account connections all at once. That can be helpful, but it can also make a simple question—“What is my actual available balance?”—harder to answer. A ledger-centered workflow keeps attention on entries and the balance they produce.
Someone who is learning to manage money may benefit from the app’s hands-on nature. Recording a purchase forces a small pause, and that pause can be educational. Instead of seeing spending only as a monthly summary, the user sees how individual decisions change the account. I would use it alongside a bank statement and a simple personal rule for saving, because the ledger itself does not replace financial planning.
It is less suitable for a person who refuses manual entry, needs automatic synchronization, or wants a single screen combining banking, investments, credit cards, and long-term goals. In those cases, a connected budgeting platform will probably save more time despite being more complex. It is also not my first choice for a large household with high transaction volume unless everyone agrees on who records what and when.
Questions I would answer before installing
Is it genuinely free to try? Yes, the app is listed as free, which makes testing its basic workflow straightforward. However, in-app purchases are listed at $1.99 per item, so I would inspect the available purchase options inside the app before assuming that every capability is included without payment.
Does it replace online banking? I would not use it that way. It is a ledger for managing account records, while the bank remains the authoritative place to confirm cleared transactions, available funds, and official account information. The app can help organize my view, but it should not be treated as a banking connection or a substitute for checking the bank.
Will it work on an older device? The listed minimum operating system is iOS 11. If the device cannot run that version, installation may not be practical. For a supported device, I would still keep the operating system and the app reasonably current so the experience is less likely to be affected by compatibility issues.
Can it help someone who uses cash or checks? That is one of the clearest reasons I would consider it. A manual checkbook approach is naturally better suited to transactions that do not appear instantly in a card or banking feed. The benefit depends on entering those transactions promptly and reviewing them consistently.
Is it better than a full budgeting app? Not universally. I prefer it when the main job is maintaining a reliable account register. I would choose a broader budgeting alternative when I need automatic imports, category analysis, shared planning, or a wider view of my finances. The trade-off is simplicity versus coverage.
My buy-or-skip verdict
My recommendation is to try Simple Checkbook Ledger when you want a focused, free-to-start way to maintain account records and you are comfortable taking responsibility for manual updates. Its value is practical rather than flashy: it can make pending commitments, cash spending, and check activity easier to keep in one running view.
I would skip it if the phrase “checkbook ledger” already sounds like too much maintenance. In that case, an automated finance app is likely to fit better, even if it includes more features than you need. I would also skip it for complex financial planning, because a simple register cannot answer every question about debt, savings, investments, or household goals.
For the right user, Simple Checkbook Ledger is a sensible utility rather than an all-purpose financial command center. The free entry point lowers the risk of testing it, while the optional $1.99 purchases mean I would judge paid value only after seeing which additions genuinely improve my routine. My final view is positive but specific: choose it for deliberate account tracking, not for automation or comprehensive budgeting.
If that distinction matches your needs, Simple Checkbook Ledger can earn a useful place in your daily money routine. If you want the app to do the tracking for you, the better decision is to look elsewhere before spending time building a ledger you will not maintain.
Gallery
Simple Checkbook Ledger Pros and Cons
- Clean
- easy-to-understand interface for tracking personal finances.
- Supports quick income and expense entries on the go.
- Useful balance history helps monitor spending over time.
- Lightweight app that runs smoothly on older devices.
- Simple layout suits users who prefer manual budgeting.
- Manual data entry can become tedious for frequent transactions.
- May lack advanced budgeting and investment-tracking tools.
- Limited automation compared with full-featured finance apps.
- No built-in bank synchronization may require extra effort.
- Users may need backups to protect their financial records.
Simple Checkbook Ledger Frequently Asked Questions
What is Simple Checkbook Ledger used for?
Simple Checkbook Ledger is designed to help you record and monitor personal finances without the complexity of a full banking app. You can enter income, expenses, deposits, withdrawals, and adjustments, then review your running balance. It is particularly useful for people who still manage a checking account manually or want a straightforward offline-style ledger for everyday transactions.
Does Simple Checkbook Ledger connect directly to my bank account?
The app is primarily intended for manual transaction tracking rather than automatic bank synchronization. In practice, you should expect to enter transactions yourself instead of granting the app access to your financial institution. This can take a little more effort, but it also gives you greater control and may reduce privacy concerns. Check the current app listing for any platform-specific import or synchronization features.
Can I use Simple Checkbook Ledger to track multiple accounts?
Simple Checkbook Ledger may be suitable for keeping separate records for different checking, savings, cash, or other accounts, depending on the version and features available on your device. Before downloading, review how account creation, account switching, and balance management work. Users who need advanced budgeting, investments, shared wallets, or detailed financial reports may find the app more limited than a comprehensive finance manager.
Is my financial information safe when using Simple Checkbook Ledger?
Because you may enter sensitive details such as balances, merchant names, and transaction amounts, privacy should be considered before use. Avoid recording full card numbers, passwords, or online banking credentials in transaction notes. Review the app’s privacy policy, permissions, backup options, and data-storage practices in the official store listing. A device passcode and regular backups can also help protect your records.
Is Simple Checkbook Ledger free, and are there any limitations?
Availability, pricing, advertisements, and included features can vary between Android and iOS versions and may change with updates. The basic ledger functions may be enough for simple transaction recording, while advanced options could require a purchase or include restrictions. Before installing, check the official store page for in-app purchases, supported devices, export capabilities, backup limitations, and whether the app is actively maintained.














